
The Loan Lowdown: Volatility shakes out new sources of liquidity for Loan investors
By Howard Cohen | 24 March 2022
Text
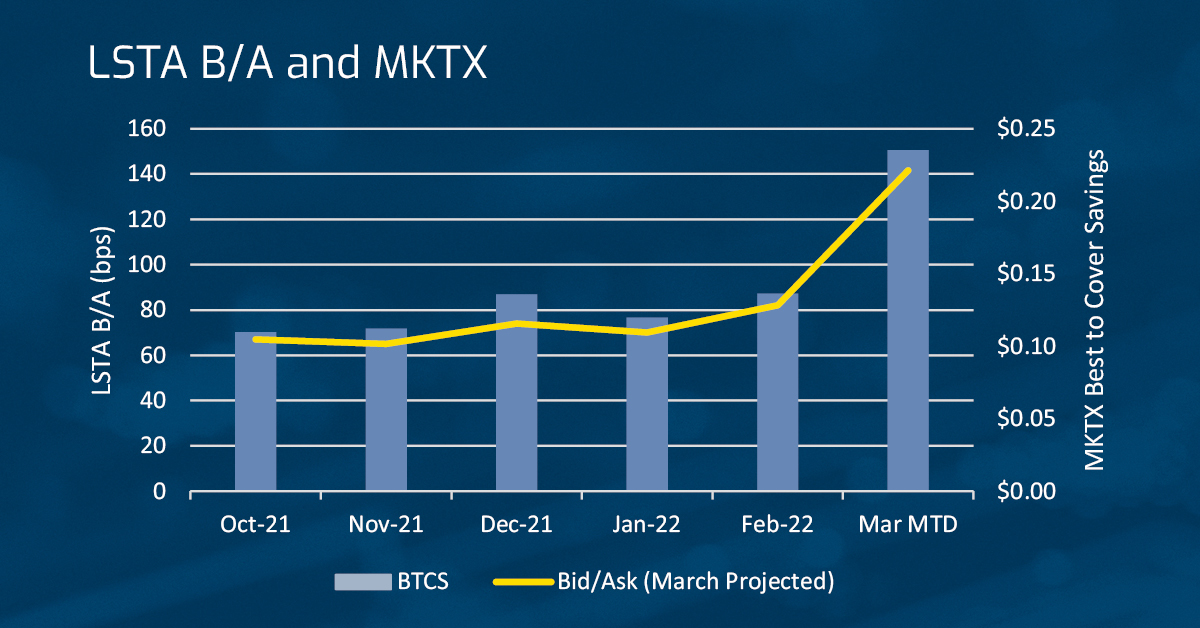
Entering the new year, the loan market felt like it was bullet proof. Supported by a hawkish environment, all time low default rates, retail inflows and a strong CLO bid had loans in the sweet spot of credit. Bid offer in the leveraged loan market had collapsed along with spreads, and accounts had difficult time sourcing paper in both primary allocations and the secondary market. In January the LSTA index reached its highest point in 15 years, however around mid-January, the softness in equities and other credit products leaked into the loan space. Concerns about recession and stagflation plagued all of leveraged finance and the crisis in Ukraine forced prices lower. The dealer community pulled back on taking risk and increased bid offer meaningfully.
Additionally, the new issue market froze as new deals were pulled. On the MarketAxess platform volumes spiked as clients looked for liquidity in new ways. The Best to Cover Savings (BTCS) a measure of clients’ savings observable in electronic trading doubled from 11.9cents in January to 23.5cents in March. Fortunately, there has been a recent turn around in loan pricing buoyed by recent Fed rate hike. Of late the new issue loan market has thawed as well with Agents being able to price new facilities again. This volatility coupled with reduced dealer liquidity encouraged the buy side to source liquidity via a new venue in the loan space.
If you’d like to continue the conversation with Howard directly, drop him a line.
Email: Hcohen@marketaxess.com | LinkedIn: linkedin.com/in/hoco13