
AxessPoint: Intraday bid/ask spreads in global corporate bond markets
Highlights
- Bid/ask spreads are wider in the morning and narrower throughout the day as trading information increases.
- The delta between opening and closing spreads was greater during the crisis, in line with wider bid/ask spreads and more volatile pricing. Additionally, spreads re-widened intraday with greater frequency.
- USHG, when compared to ASIA USD and EURO EUR, showed the most spread tightening intraday.
Wider bid/ask spreads in the morning
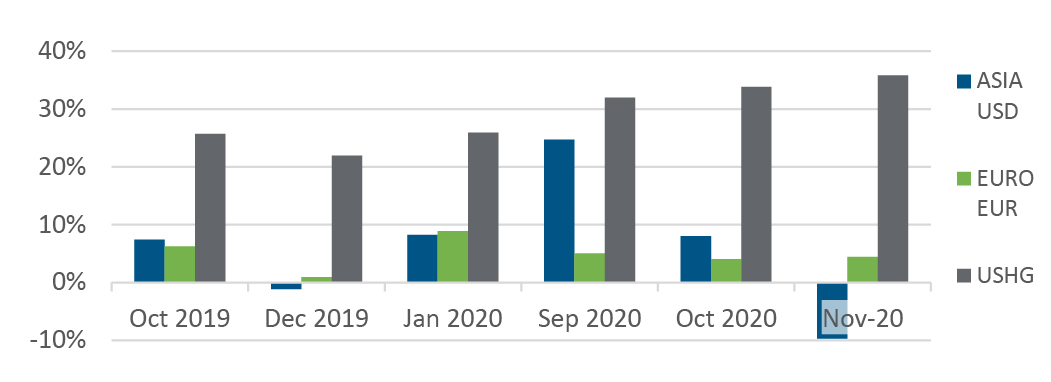
When measuring the median CP+ bid/ask spread by hour of the day across global corporate bond markets, we observe that CP+ bid/ask spreads begin the day wider and tighten throughout the day. As more market data becomes available throughout the day, bond pricing moves towards a consensus, leading to less uncertainty and tighter bid/ask spreads. For example, USHG in January 2020, median 8am – 4pm (NY Time) bid/ask spread tightened by $0.077, or 26% of the opening bid/ask spread. We observed the same phenomena in other regions as well; with ASIA USD spreads being $0.0252 (11.7%) and EURO EUR at €0.0162 (11.2%) for the same period leveraging Singapore time for ASIA bonds and London Time for EURO.
Figure 1. Regional median intraday bid/ask spreads in price. Bonds quoted on price basis.
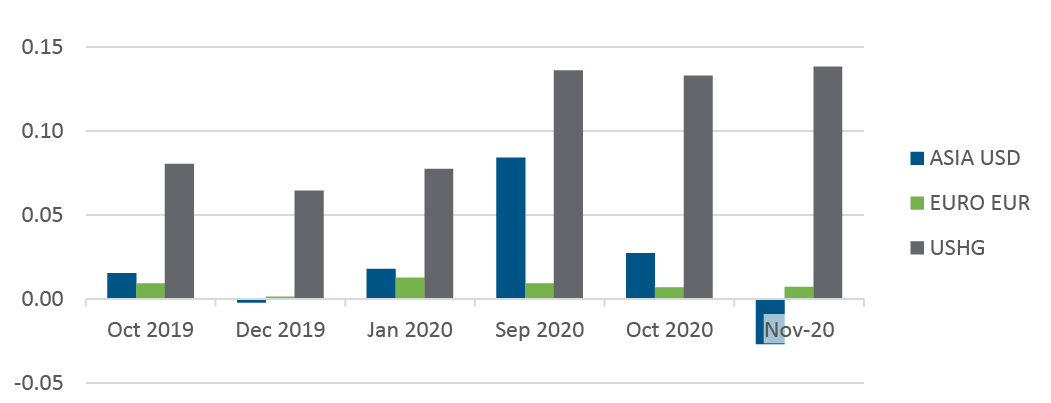
Figure 2. Percentage Tightening of Intraday Spreads, Higher percentages indicate spreads moving more significantly over the day.
Volatility drove bid/ask spreads higher
Pre-crisis intraday bid/ask spread differentials were comparatively lower than during the height of the crisis. As we noted in a previous AxessPoint, bid/ask spreads increased over the crisis and have slowly tightened since. Intraday bid/ask spreads also experienced a dislocation due to the volatility, where markets tightened over the day, but appeared to widen into the close, potentially due to news that introduced fresh uncertainty.
Figure 3. USHG intraday CP+ bid/ask spread behavior before, during and after the crisis.
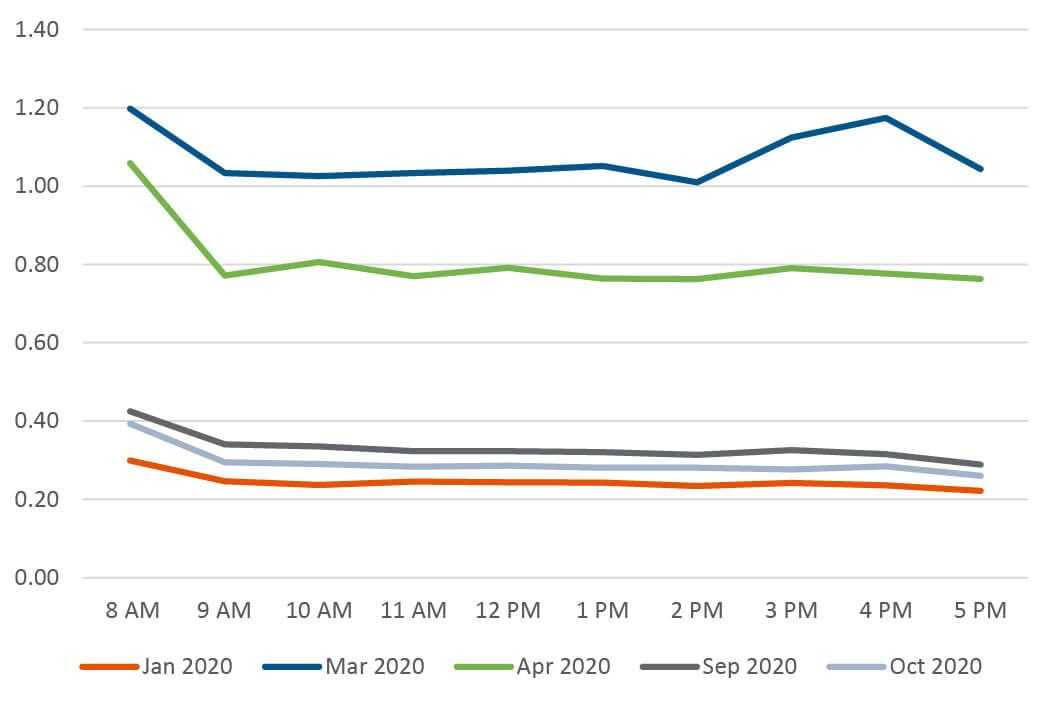
Globally, higher volatility drove bid/ask spreads wider over the day, and increased costs into the day’s close. In March 2020 specifically, frequent global news headlines around the pandemic resulted in multiple intraday widenings as participants tried to digest market impact in real time. In April, bid/ask spreads opened even wider at the start of the day, but with fewer spikes as the world settled into the new normal. April opening bid/ask vs. normal times was also multiples higher in all regions.
Redefining real-time bond pricing
CP+™ is MarketAxess’ proprietary AI powered pricing engine for corporate bonds. It produces an unbiased, two-sided market for more than 29,000 instruments globally. Updated every 15 to 60 seconds, the engine generates nearly 30 million levels per day covering 90-95% of trading activity in its markets.
For questions or follow-up, email our data scientists at research@marketaxess.com.