
AxessPoint: Adjusting to a new normal in European credit markets
Highlights
- Since the market sell off caused by the COVID-19 global pandemic, bid/ask spreads in European credit markets are settling at twice their pre-crisis levels.
- Bid/ask spreads peaked at €0.43 for EUR IG, €0.85 for EUR HY, £0.61 for GBP IG, and have since fallen by approximately 1/3ʳᵈ. With upcoming fiscal and monetary stimulus in Europe, spreads are settling.
Stabilising bid/ask spreads
Until the end of February, European bid/ask spreads were among the tightest across major markets. For example, at the start of February the Composite+™ spread for EUR IG was at €0.09, while that for EUR HY was €0.20, and GBP IG was £0.21.
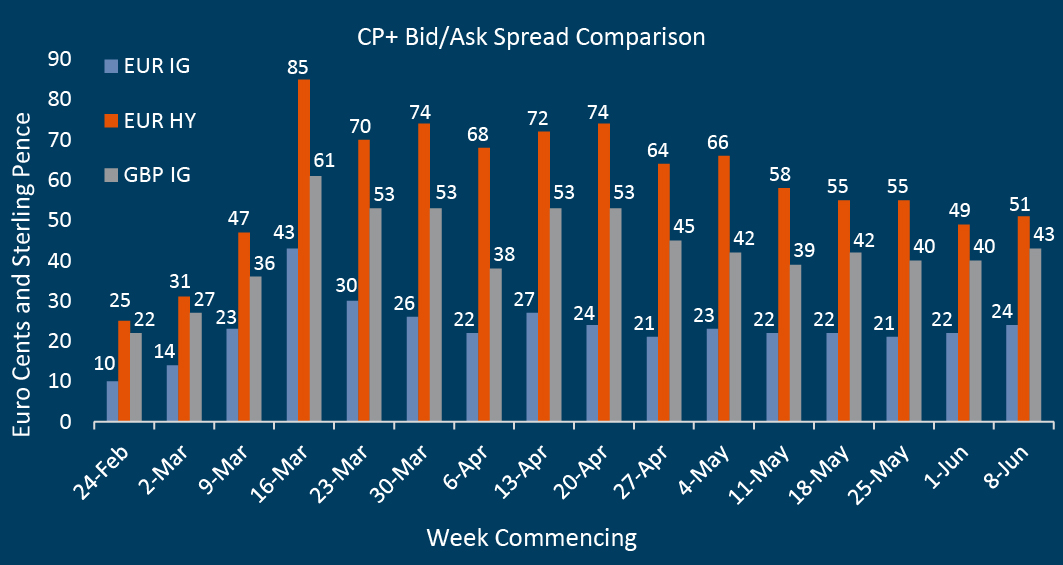
At the height of the crisis, European price spreads saw increases of +377% in EUR IG (€0.09 to €0.43), +325% in EUR HY (€0.20 to €0.85), and +190% in GBP IG (£0.21 to £0.61).
Following this, with the number of new COVID-19 cases declining in Europe and a series of newly announced ECB monetary stimulus packages, bid/ask spreads started falling and have now stabilized. European bid/ask spreads remain 2-3x higher than pre-crisis, with EUR IG at €0.22 vs €0.09, EUR HY at €0.49 vs €0.20, and GBP IG £0.40 vs £0.21 pre-crisis.
Divergence in bid/ask by sector and maturity
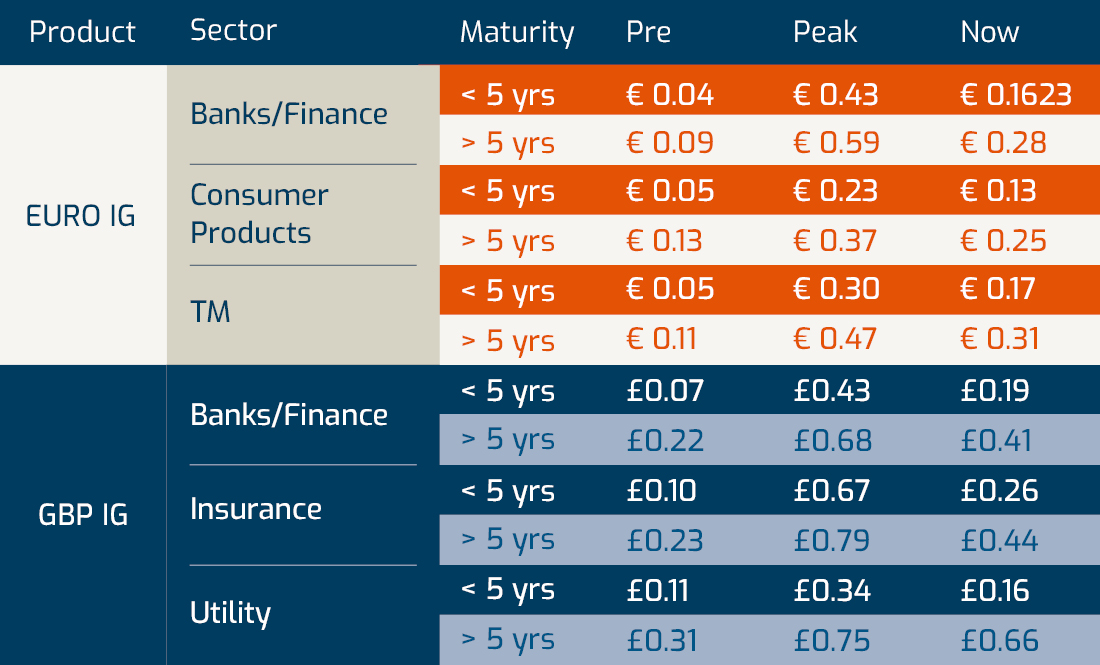
There has been a divergence between different sectors and maturities, with some recovering slower than others. For example, the bid/ask for short-end maturity EUR-Financials still remains four times higher (€0.16 vs €0.04 pre-crisis), while the short end Sterling Utility sector is only one and a half times higher than that pre-crisis (£0.16 vs £0.11 pre-crisis); see below table.
Top traded investment grade sectors by currency
Adjusting to a new normal
As the global economy begins to open and people start to adjust to a new working environment, credit markets have likewise adjusted. After March peaks, bid/ask spreads have stabilized at levels roughly twice that pre-crisis, with some sectors tightening quicker than others. With European fiscal and monetary stimulus on the horizon, spreads could remain at these elevated levels for the foreseeable future.
Redefining real-time bond pricing
Composite+ (CP+) is MarketAxess’ proprietary AI-powered pricing engine for corporate bonds. It produces an unbiased, two-sided market for more than 25,000 instruments globally. Updated every 15 to 60 seconds, the engine generates over 30 million levels per day covering 90-95% of trading activity in its markets.
For questions or follow-up, email our data scientists at research@marketaxess.com.