
AxessPoint: Global credit market bid/ask spreads return to normal
Highlights
- Median CP+™ bid/ask spreads are significantly lower in March 2021 compared to March 2020 at the height of the crisis. The bid/ask spreads are now closer to the pre-crisis levels.
- Most major markets’ bid/ask spreads have reverted to pre-crisis levels or lower, such as EUR IG whose spreads are now 38% lower than pre-crisis. USD EM stands out as an exception as spreads remain 23% higher compared to pre-crisis
CP+ bid/ask spread comparison

At the peak of the COVID-19 crisis in March 2020, bid/ask spreads spiked across all major markets (See “A new normal for global credit market bid/ask spreads”). Bid/ask spreads have since continued their trajectory falling back to pre-crisis levels a year later. USD IG is now at 2.4 bps, USD HY is at 25 cents, USD EM is at 27 cents, and EUR IG at 8 Euro cents indicating a return to the pre-crisis tighter spread regime.
From March 2019 to March 2021, credit spreads, measured by CP+, saw changes of:
- -17% for USD IG (2.9 bps to 2.4 bps);
- -8.7% for USD HY (28 cents to 25 cents);
- +23% for USD EM (22 cents to 27 cents);
- -38% for EUR IG (13 Euro cents to 8 Euro cents).
USD-denominated EM CP+ bid/ask spread comparison
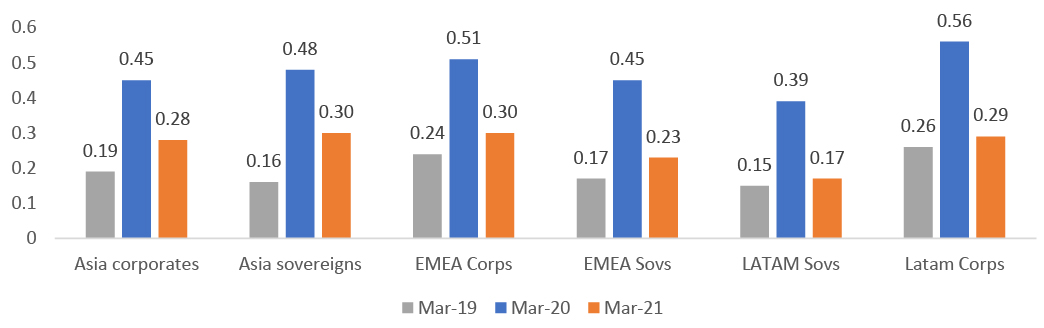
The increase in bid/ask spread in USD EM appears to be uniform with some variance in magnitude. All sectors’ bid/ask spread remain elevated compared to their pre-crisis levels.
From March 2019 to March 2021, USD EM bid/ask spreads across sector, measured by CP+, saw increases of:
- +47% for Asia Corporates (19 cents to 28 cents);
- +88% for Asia Sovereigns (16 cents to 30 cents);
- +25% for EMEA Corps (24 cents to 30 cents);
- +35% for EMEA Sovs (17 cents to 23 cents);
- +6.3% for LATAM Sovs (16 cents to 17 cents);
- +12% for LATAM Corps (26 cents to 29 cents).
Bid/ask spreads across major products have largely returned to pre-crisis levels or lower except for USD EM. For USD EM, across all sectors, bid/ask spreads remain higher than pre-crisis levels. This is particularly pronounced in Asia sovereigns where spreads remain 88% higher now compared to pre-crisis.
Redefined real-time bond pricing
CP+ (fka Composite+) is MarketAxess’ proprietary AI-powered pricing engine for corporate bonds. It produces an unbiased, two-sided market for more than 30,000 instruments globally. Updated every 15 to 60 seconds, the engine generates nearly 30 million levels per day covering 90-95% of trading activity in its markets.
For questions or follow-up, email our data scientists at research@marketaxess.com.