
Blockbusting Part 4 | Block execution in USHG
This AxessPoint, Blockbusting Part 4, provides an update on the liquidity profile of block-sized trades on MarketAxess, with a specific focus on the $5mm-$10mm segment in US High Grade (blocks) for maturities over 5 years. In response to client inquiries and driven by the record trade volume in this size range during Q1 of 2024 on our platform, we are pleased to share our analysis on the quality of execution for block trades on our platform.
Highlights and objectives
This AxessPoint provides an update on the liquidity profile of block-sized RFQ trades on MarketAxess, with a specific focus on the $5mm-$10mm segment in US High Grade (blocks) for maturities over 5 years . In response to client inquiries and driven by the record trade volume in this size range during Q1 of 2024 on our platform, we are pleased to share our analysis on the quality of execution for block trades on our platform. Unless otherwise stated all results are for H1 2024.
The analysis will show that there is:
No deterioration in the quality of execution from slightly above $1mm all the way up to $10mm.
Minimal impact from the size of the inquiry in terms of hit rates, prices back or transaction costs.
For this analysis, we have excluded trade sizes below $1mm, where algorithmic trading activity is more prevalent and trading patterns differ. We have evaluated the quality of execution using various metrics, including the number of firm prices back on larger trades over time, TCA vs. Trace, and a graph showing hit rates and prices back vs. maturity in the $5mm+ segment.
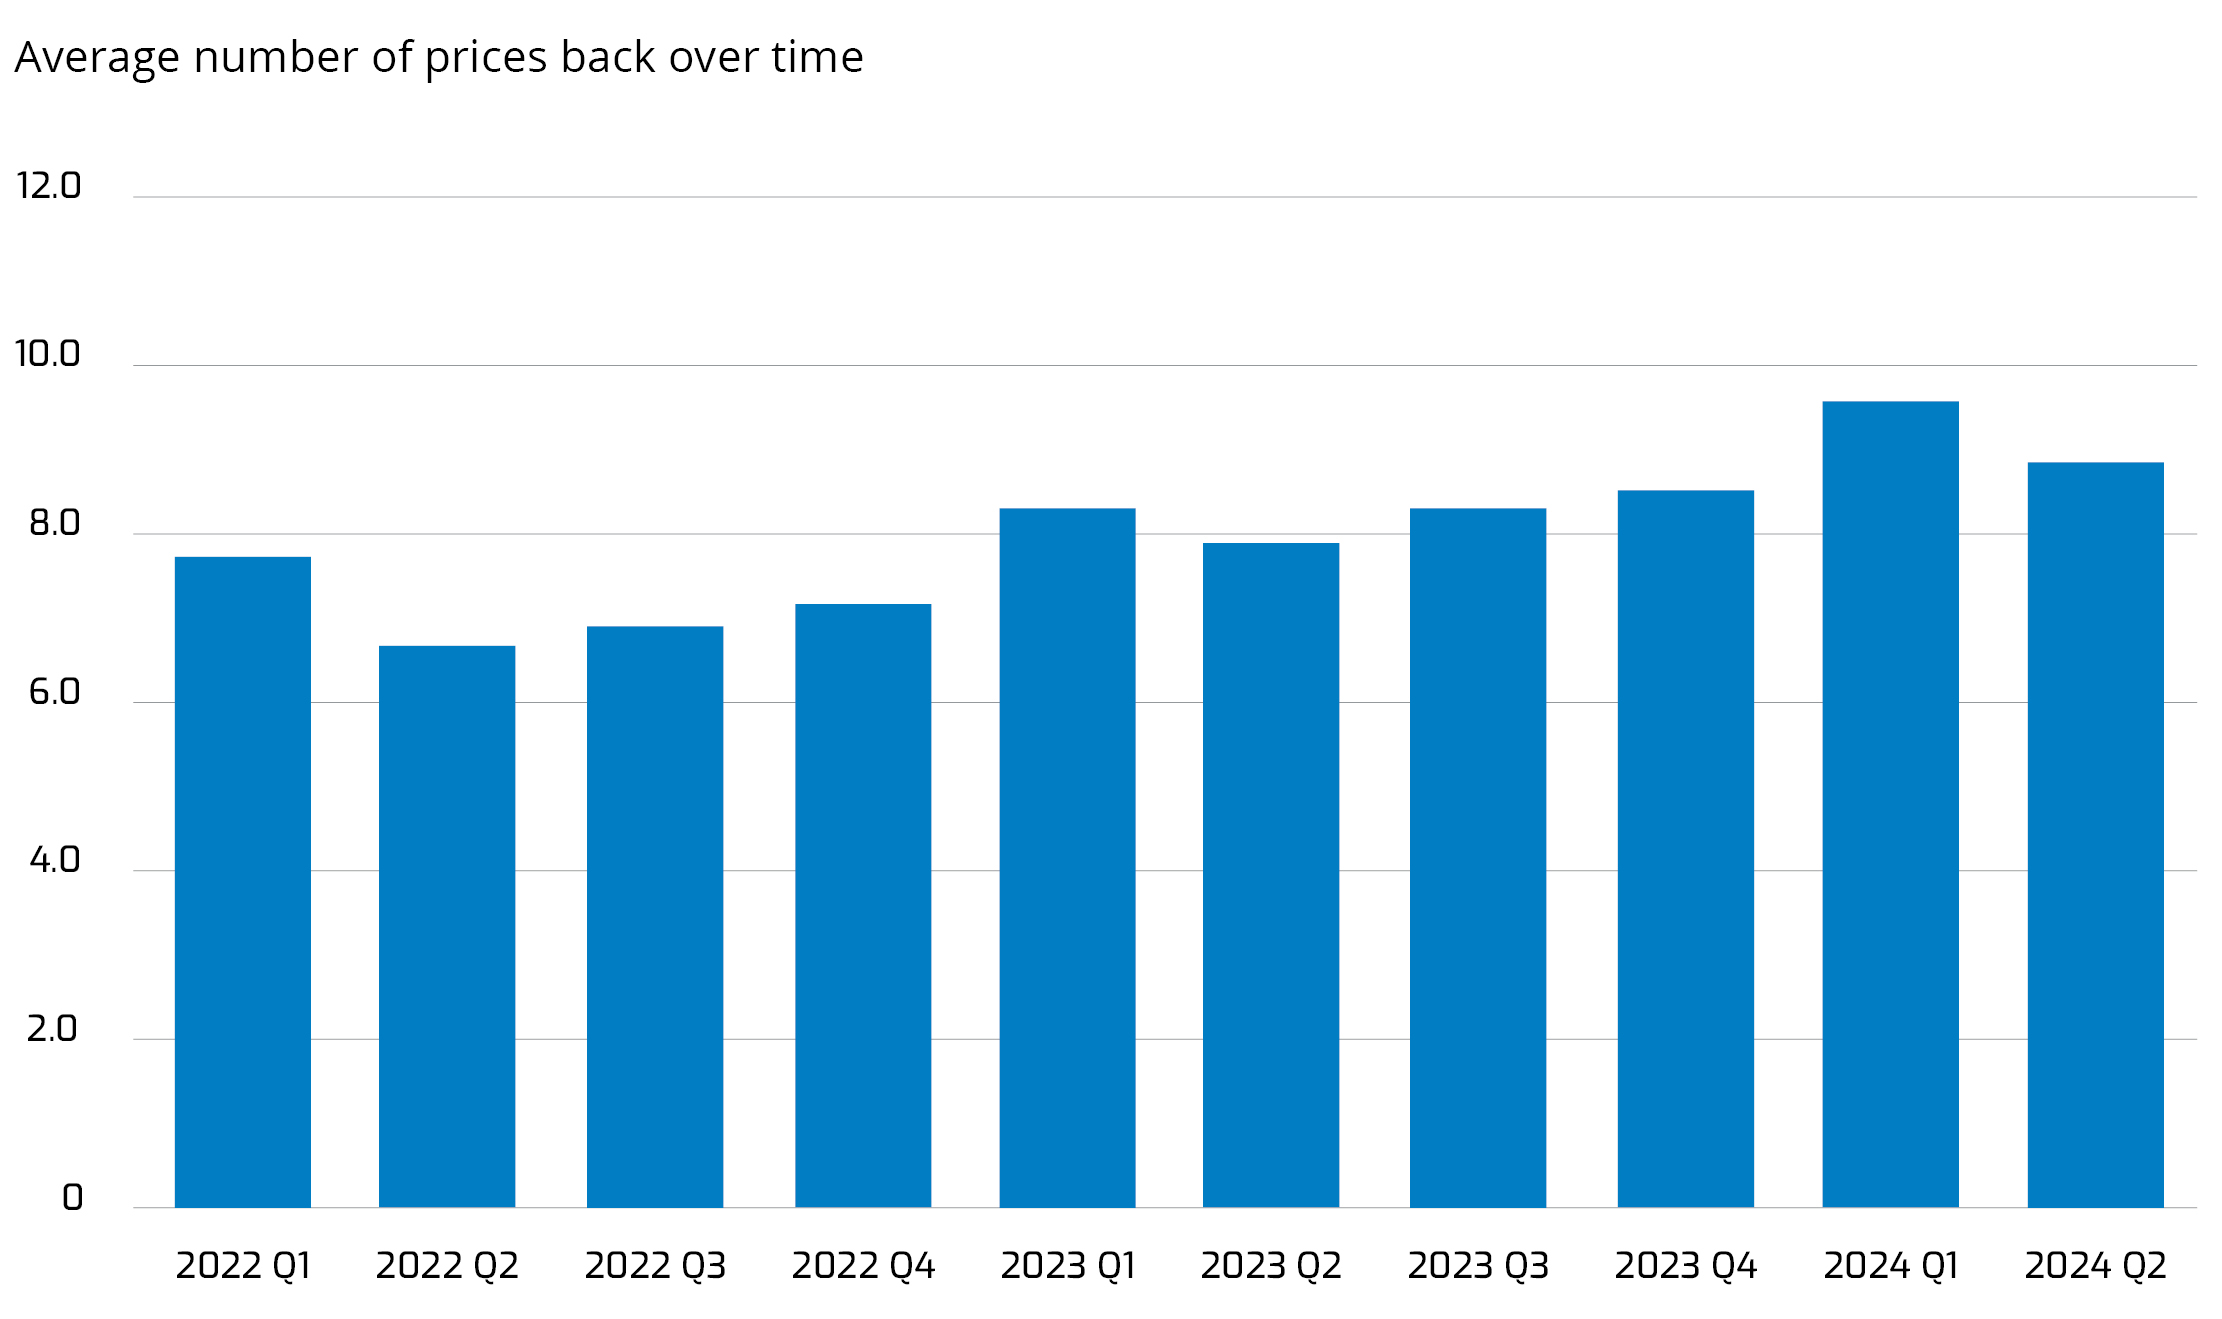
Prices back on $5-10mm trades over time on the MarketAxess platform
1We restrict to maturities over 5 years were dealers trade ‘flow’ as opposed to ‘technicals’ around bond ownership.
The graph shows a clear trend in the number of firm prices back on larger trades we are seeing on the platform. This increase shows the growing willingness among dealers to quote and trade these sizes on MarketAxess.
Prices back and TCA across size buckets on traded inquiries
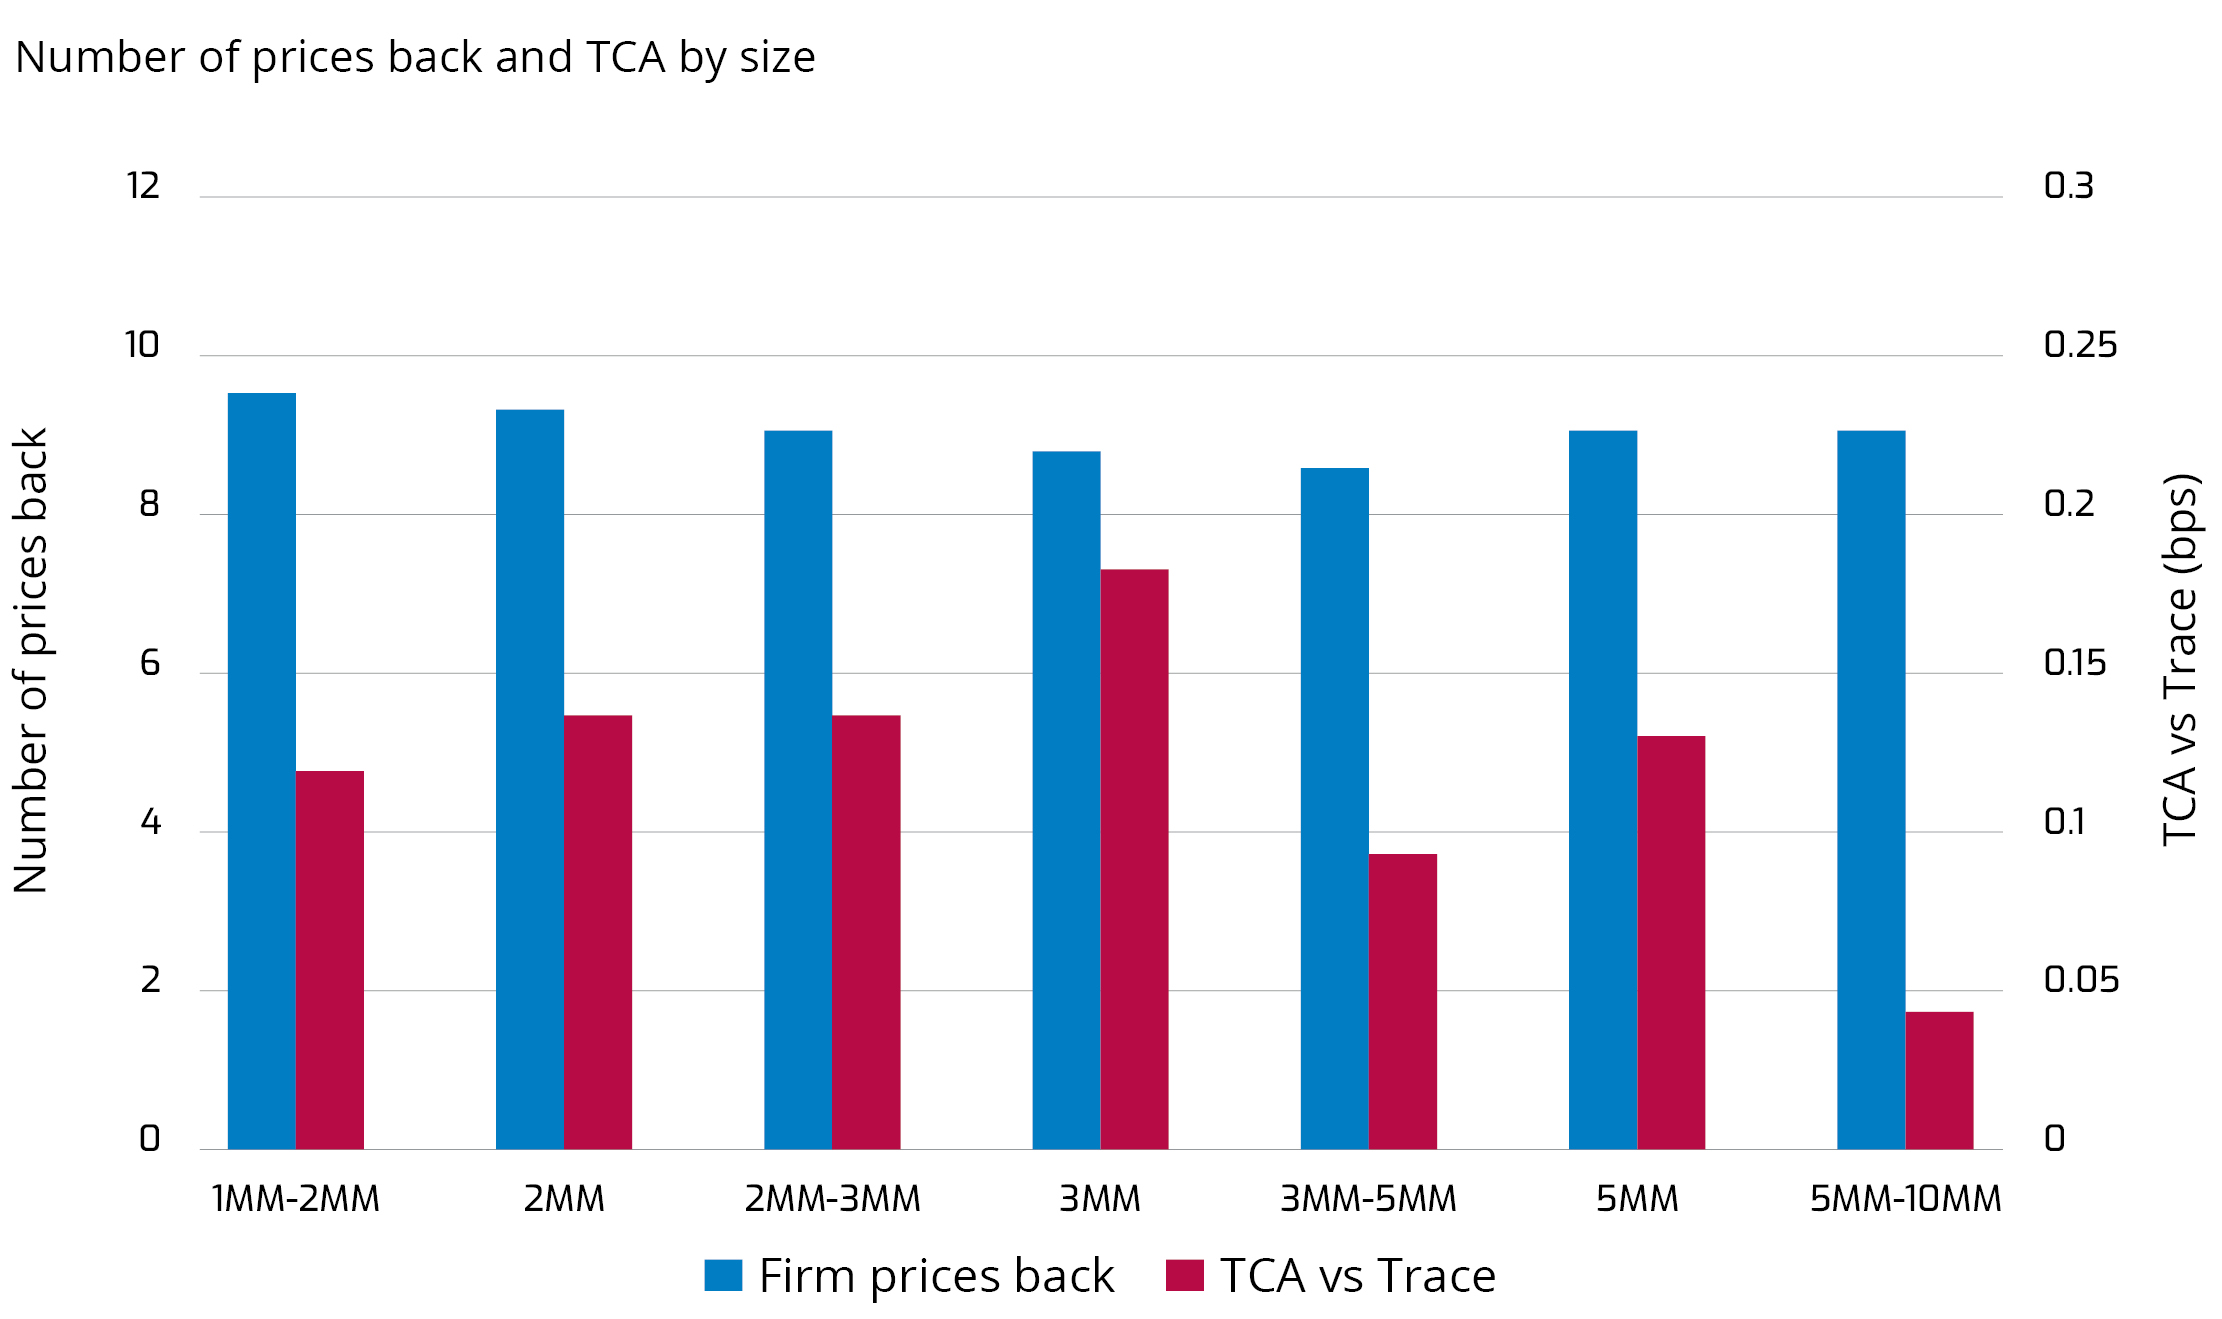
We also want to look at the data across various size buckets. Above, we have plotted the average number of prices back again, and we have added the realized TCA on trades for these categories. We see limited drop-off in dealer quotes at any size, with even the highest traded amounts showing healthy amounts of prices back on executed trades. Looking at the cost analysis, TCA vs Trace remains positive for trades all the way up to $10mm.
Bond maturity
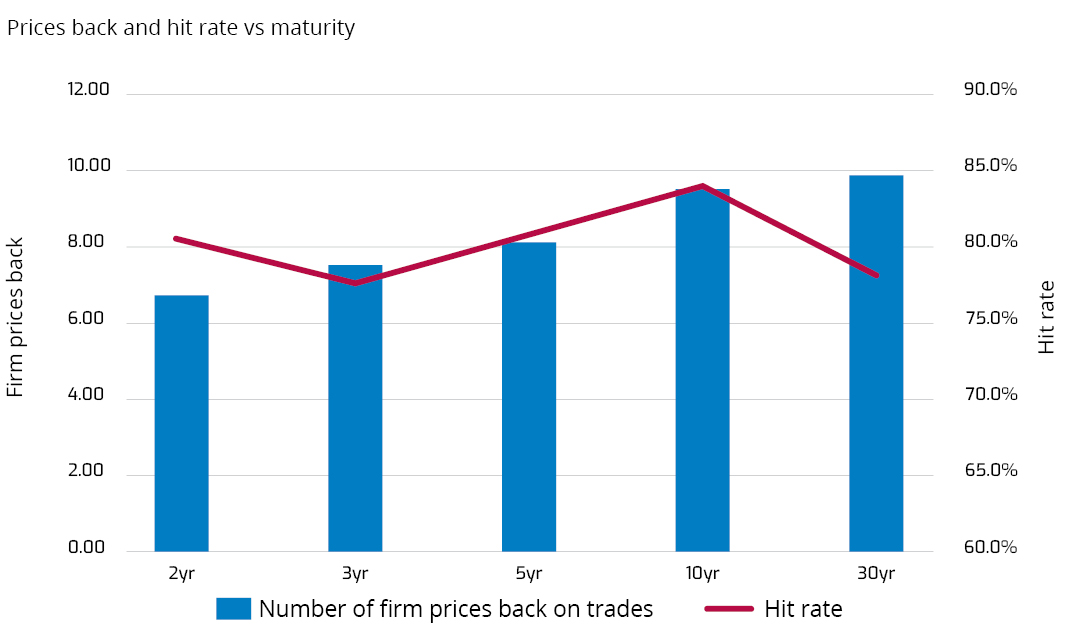
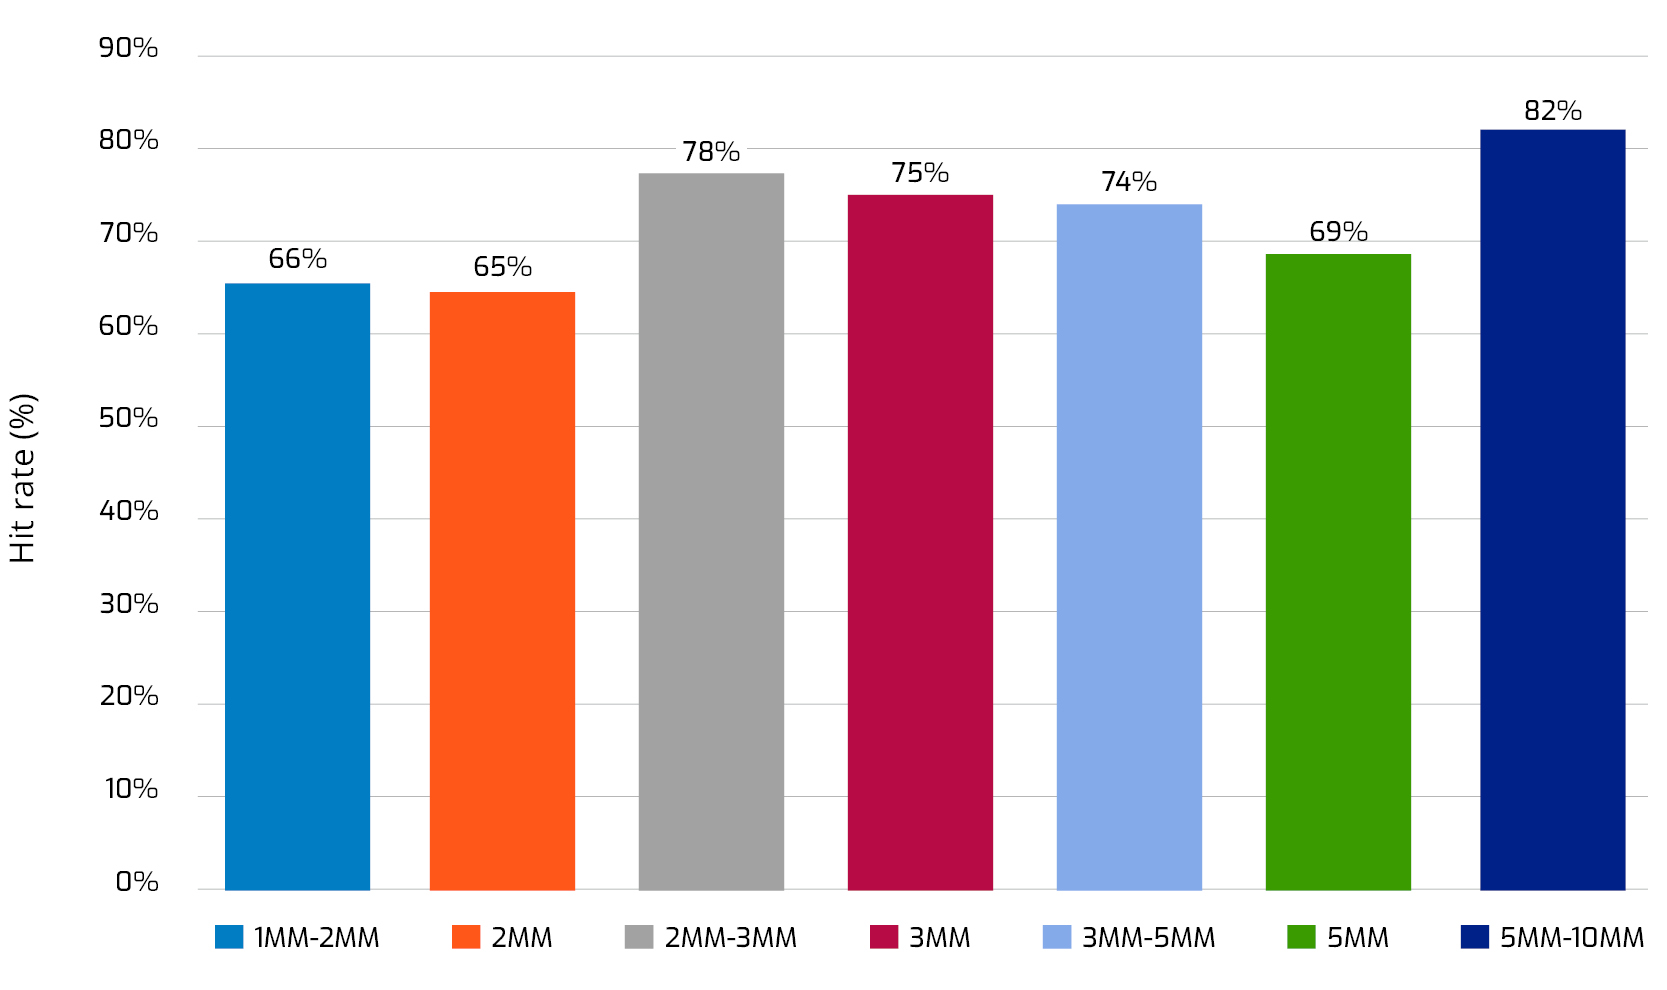
Having focused on some of the characteristics of the inquiry, we now look at the maturity of the traded bonds. This graph shows hit rates and average number of firm prices back for trades in the $5mm-10mm segment across maturities. It reveals that execution is very good across the board, with even more prices coming back for higher maturity buckets.
Trades vs CP+™
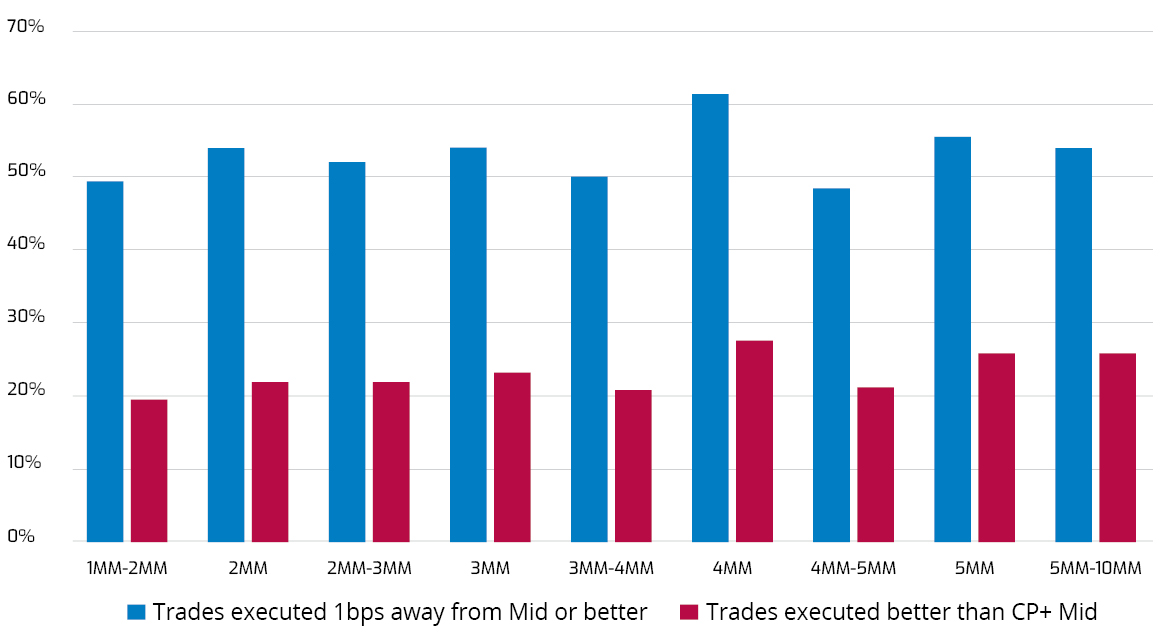
Finally, we analyze where trades are executed compared to MarketAxess’ proprietary pricing product CP+. The graph below shows trades executed at CP+ mid or better, as well as trades done 1bps away from CP+ mid and better. For block trades, we see 26% trading at mid or better, which are some of the highest values in the >$1mm range. This shows there are plenty of occasions where counterparties are willing to step up to be competitive at these large sizes.
Percentage of trades executed 1bps away from CP+ mid and better is 54.3% for blocks, and the cross-bucket graphs again shows there is very consistent quality of prices for all size buckets.
We also see consistently high hit rates across size buckets, again with highest values in the $5-10mm bucket.
The data demonstrates that MarketAxess provides a highly liquid and competitive platform for block-sized trades in the US High Grade market, with a strong track record of execution quality and a growing number of dealer prices back.
Conclusion
The analysis shows that trade size has little impact on execution quality on inquiries in US High Grade market between $1m and 10mm. Dealer willingness to quote and trade larger sizes is growing and TCA vs. Trace remains positive for trades up to $10mm.
Maturity seems to have a relatively small impact on either hit rates or prices back. Overall, MarketAxess provides a highly liquid platform for block-sized trades with strong execution quality and growing dealer prices back.
For questions or follow-up, email our data scientists: